- Decisions in as little as2 hourson complete files
- Funded in as little as24 hoursafter you sign
- Collateral requiredNone*advances are based on future sales
Merchant cash advance offers from multiple funders, with one application
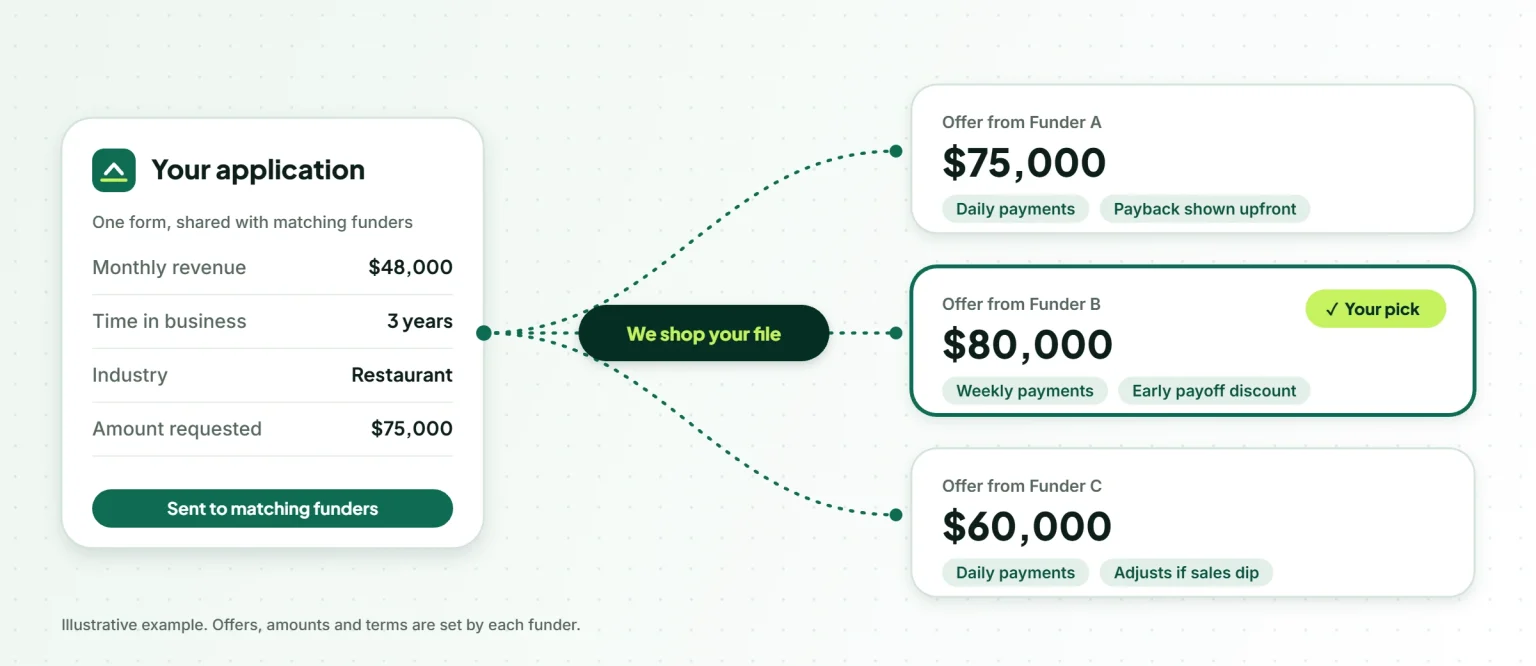
Funding Today is a business funding broker, not a lender. Tell us about your business once and we present your file to funders in our network, so you can compare merchant cash advance offers from $10,000 to $2,000,000 and choose the one that fits.
Check my options- No hard credit inquiry to check your options
- Use funds for inventory, payroll, equipment, repairs and growth
- Options may be available for credit scores as low as 500
- No cost to apply and no upfront broker fees
*Timing depends on the funder and how quickly documents arrive. Advances are based on future sales, so funders generally don’t ask you to pledge real estate or equipment. Most file a UCC financing statement on business receivables and may ask for an owner guarantee.
Check your funding options
Three short steps. It takes a few minutes and there’s no obligation.
- SSL encrypted
- No hard credit pull
- No obligation
Your details go only to funders reviewing your request. We never sell them to marketing lists.
How Funding Today gets you a merchant cash advance
A merchant cash advance gives your business a lump sum now in exchange for a share of its future sales. We do the shopping; you make every decision.
Share a few numbers
Answer three short sets of questions about your revenue, time in business and goals. Keep your last 3 to 4 months of business bank statements handy.
We match you with funders
An advisor reviews your request and presents it to funders whose guidelines fit your business, so you don’t repeat the same application again and again.
Compare, sign, get funded
Weigh each offer’s total payback, payment schedule and terms. Once you sign with the funder you pick, money can land in as little as 24 hours.
What will a merchant cash advance cost? Run the numbers
Most advances are priced with a factor rate instead of an interest rate: multiply the advance by the factor rate to get the total you’ll pay back. Enter the terms of any offer to see the payment size and an approximate APR.
Estimated total payback
- Cost of the advance$22,500
- Payment each business day$516
- Number of payments189
- Approximate APR—
Illustrative only, not an offer or a quote. Funding Today doesn’t set rates; each funder sets its own factor rate, fees and terms. Daily estimates assume 21 business days a month. The APR is an approximation that assumes equal payments and no fees.
Want the full picture? Our detailed calculator adds fees, your monthly deposits and an SBA loan comparison, then emails you a report.
Open the detailed MCA calculatorIs a merchant cash advance the right tool for your business?
An advance is fast and flexible to qualify for, and it usually costs more than bank financing. Here’s how to tell whether it makes sense right now.
Often a strong fit when
- Your business has steady monthly deposits or card sales
- You need capital within days, not the weeks a bank can take
- The money pays for something with a clear return, like inventory, an equipment repair or a large order
- Your credit history makes a bank approval unlikely for now
Think twice when
- The funds would cover ongoing losses rather than a specific need
- You already carry two or more advances
- A bank loan, SBA loan or credit line is realistic and you can wait for it
- A daily or weekly payment would squeeze your cash flow too hard
If another type of financing looks like a better match for your situation, your advisor will tell you so.
What funders typically look for
Every funder sets its own guidelines, and requirements change with your industry and the amount you request. These are the factors that matter most.
Monthly revenue
Around $10,000 a month is a common starting point, not a hard minimum. Offers are usually sized from your average deposits.
Credit history
Options may be available for scores as low as 500. Banking activity often matters as much as the score itself.
Time in business
A longer track record usually opens more options and better terms, though newer businesses can still qualify with some funders.
Location
We work with businesses in every state and Washington, D.C., except California.
Have these ready
- Your last 3 to 4 months of business bank statements
- A government-issued photo ID
- Your business’s legal name, address and tax ID (EIN)
- Business bank account details for funding
Put the funds to work
Merchant cash advance vs. other business funding
Speed and easier qualifying come at a price. Use this side-by-side to decide which product fits the job.
| Merchant cash advance | Bank term loan | SBA 7(a) loan | Business line of credit | |
|---|---|---|---|---|
| Time to funds | As little as 24 hours after signing | Often several weeks | Often several weeks or longer | Days to weeks for approval, then draw as needed |
| Paperwork | Short application and recent bank statements | Financial statements, tax returns, often collateral | Extensive, including SBA forms and financials | Financial statements and periodic reviews |
| Credit focus | Revenue and deposits weigh heavily; options as low as 500 | Strong credit usually expected | Strong credit and cash flow | Good credit usually expected |
| How you repay | Fixed daily or weekly remittance, or a share of card sales (varies by funder) | Fixed monthly payments | Fixed monthly payments over a longer term | Interest on what you draw, then repay and reuse |
| Pricing | Factor rate; usually costs more than bank financing | Interest rate and fees | Interest rate within SBA limits, plus fees | Interest on the balance, plus fees |
| Typical size | $10,000 to $2,000,000 through our network | Varies by lender | Up to $5 million per 7(a) loan | Varies by lender |
| Best for | Speed and flexible qualifying | Planned, larger investments | Long-term growth at lower cost | Recurring short-term needs |
General comparison only; terms vary by provider. SBA loan limits from the U.S. Small Business Administration.
Industries we work with
If your business takes in steady revenue, there’s a good chance a funder in our network works in your field.
Small-business funding news
Credit conditions and funding rules change often. Here’s what shifted recently, with a link to each original source.
Owners report paying more for short-term credit
NFIB’s September survey put the average short-term loan rate at 8.2%, up 0.7 points, and more owners said their latest loan cost more.
SBA’s updated 7(a) and 504 lending rules take effect
SOP 50 10 8.1 now governs SBA 7(a) and 504 loans as of October 1. Industry coverage reports stricter conditions for using an SBA loan to pay off a merchant cash advance.
Small-business loan balances grow while banks tighten
New small-business loan balances rose 8.5% from a year earlier in the second quarter, yet a net 8% of surveyed banks tightened their standards.
SBA raises the combined 7(a) and 504 cap to $10 million
Borrowers can now hold up to $10 million in combined 7(a) and 504 loans, double the previous $5 million limit.
Texas sets a registration deadline for MCA providers and brokers
Providers and brokers of sales-based financing must register with the Texas Office of Consumer Credit Commissioner by December 31, 2026.
New York sues an arbitration service tied to MCA collections
The attorney general alleges the platform presented itself as neutral while working with funders. Read the dispute clause in any offer before you sign.
A funding broker that works for your business
Funding Today gives business owners something a single bank or funder can’t: a look at several offers before committing to one. We’re not a lender, so we don’t advance money or underwrite your file. Our job is to understand what your business needs, put your request in front of funders in our network that fit it, and help you compare their offers clearly.
The funder you choose pays us, so applying costs you nothing up front. Any agreement you sign is directly between your business and that funder.
- Straight talk on cost: total payback, payment size and early payoff terms before you sign
- No rate quotes before a funder reviews your file, because rates vary by funder
- Your information goes only to funders reviewing your request
- We’ll tell you when an advance isn’t the right move
Six questions to ask before you sign any advance
- What is the total payback amount, and what factor rate is it based on?
- Is the payment a fixed daily or weekly amount, or a percentage of sales?
- Does the contract allow payments to be adjusted if sales drop?
- Is there a discount for paying the balance off early?
- Which fees come out of the funded amount, such as origination or ACH fees?
- How are disputes handled, and does the contract require arbitration or a confession of judgment?
Merchant cash advance questions, answered
Is Funding Today a lender?
No. Funding Today is a business funding broker. We don’t advance our own money or underwrite files. We present your request to funders in our network, and any agreement you sign is between your business and the funder you choose. If you accept an offer, that funder compensates Funding Today.
What is a merchant cash advance?
A merchant cash advance gives your business a lump sum in exchange for a portion of its future sales. Instead of a monthly loan payment, the funder collects a fixed daily or weekly amount, or a percentage of card sales, until the agreed total is repaid. Most advances are written as a purchase of future receivables rather than a loan, and how they’re treated legally depends on state law.
How much funding can my business get?
Advances through our funder network range from $10,000 to $2,000,000. Funders usually size an offer from your average monthly revenue, how long you’ve been in business and how your bank account has performed.
How fast can I get the money?
After you sign with a funder, money can arrive in as little as 24 hours. Timing depends on the funder and how quickly your documents come in.
Will checking my options affect my credit?
Checking your options doesn’t involve a hard credit inquiry. Some funders run their own credit check before final approval, and your advisor can tell you which ones do.
What credit score do I need?
Options may be available for credit scores as low as 500. Revenue and banking history often count as much as your score, and requirements vary by funder, industry and amount.
How much does a merchant cash advance cost?
Each funder sets its own price, usually as a factor rate. For example, a $50,000 advance at a 1.30 factor rate means $65,000 in total payback. Ask every funder for the total payback, the payment amount and any fees, and use the estimator on this page to compare offers by approximate APR. Advances typically cost more than bank financing.
How are payments collected?
Most funders collect a fixed amount each business day or each week from your business bank account. Others take a set percentage of card sales. Payment structures vary by funder, so compare them closely before you sign.
Can I pay off an advance early?
Early payoff terms vary by funder. Some offer a discount for paying early and others don’t, so ask before you sign.
Do I need collateral for a merchant cash advance?
Usually not in the traditional sense. Because an advance is a purchase of future sales, funders generally don’t ask you to pledge real estate or equipment. Most do file a UCC financing statement on business receivables and may ask for an owner’s guarantee, so read those terms before you sign.
Which states do you work with?
We work with businesses in every U.S. state and Washington, D.C., except California.
Do you charge any fees?
There’s no cost to apply and no upfront fee. If you accept an offer, the funder pays Funding Today. Any fees the funder charges are listed in its offer and agreement.
What documents will I need?
Usually your last 3 to 4 months of business bank statements, a government-issued photo ID and basic details about your business. Some funders ask for more on larger amounts.
See what your business qualifies for
One application, multiple funders and no cost to apply. It takes a few minutes, and you’re never obligated to accept an offer.
- No cost to apply
- No hard credit inquiry
- No obligation to accept
Sources and further reading
- U.S. Small Business Administration: 7(a) loans
- Federal Reserve: Senior Loan Officer Opinion Survey, July 2026
- Federal Reserve Bank of Kansas City: Small Business Lending Survey, Q2 2026
- Federal Trade Commission: cash advance firm settlement (2021)
- New York Attorney General: Yellowstone Capital settlement (2025)
- Texas Finance Code chapter 398: commercial sales-based financing
Funding Today summarizes these sources for general information. Nothing on this page is legal, tax or financial advice.